The Best Credit Cards for Business Class Travelers in 2026
Forget the ranked lists of 'best travel cards.' Here's what actually matters when you're flying premium cabins forty times a year: which perks convert to real money, which lounges are worth the walk, and how a card fits around buying the business class fare itself.
CEOFLIGHTS Team15 min read
Quick summary
The two cards worth carrying in 2026 (Capital One Venture X and Amex Platinum) charge $395 and $895 respectively, but their real cost after credits is often under $100 a year
Lounge access isn't one perk, it's four different networks (Priority Pass, Centurion, Capital One Lounges, Plaza Premium) with wildly different quality and crowding
Credit cards are a mileage and insurance tool, not a booking engine; for the actual seat, consolidator fares through CEOFLIGHTS routinely beat portal pricing by 30-40%
Most "best credit cards for travelers" content reads like it was written by someone who flies twice a year and just discovered Priority Pass. It ranks cards by welcome bonus size, throws in a lounge photo, and calls it a day. That's fine if you're picking a card for a honeymoon. It's useless if you're the kind of person who books eight business class tickets a quarter and can tell a Club Suite from a Qsuite with the lights off.
So let's do this differently. Instead of ranking cards, we're going to walk through the perks that actually move the needle for someone flying premium cabins regularly, and be honest about which ones are marketing dressing versus which ones save or make you real money. Then we'll talk about the part nobody covers: how a credit card fits into a strategy built around consolidator fares.
The Two Cards Worth Actually Carrying
There's no shortage of travel cards on the market, but for frequent premium cabin flyers, the field narrows fast. The Capital One Venture X ($395 annual fee) and the American Express Platinum ($895 annual fee, up from $695 after Amex's 2025 refresh) dominate the conversation for a reason: they're the only two mainstream cards that pair a real lounge network with credits substantial enough to meaningfully offset the fee.
Everything else, the Chase Sapphire Reserve, the various co-branded airline cards, the Citi Prestige successors, plays a supporting role at best. They're fine for earning on category spend. They're not the backbone of a premium travel strategy.
At $395 and $895 a year, the Venture X and Amex Platinum are the only two mainstream cards pairing a real lounge network with credits large enough to offset most of the fee.
Here's the uncomfortable truth about both flagship cards: neither one gets you into business class. Not directly, anyway. What they get you is compounding value around the trip: lounges before the flight, insurance during it, and points that can occasionally buy a seat you'd otherwise pay four figures for. The actual ticket, more often than not, still needs to be bought well. That's a separate skill, and it's one we'll come back to.
$1,290Annual fee gap between Venture X and Amex Platinum, before credits
Lounge Access Isn't One Perk. It's Four.
This is where most comparison articles get lazy. They say "lounge access" like it's a single binary feature. It isn't. In 2026 there are at least four distinct lounge ecosystems tied to premium cards, and they are not remotely equal.
Priority Pass, included with both flagship cards, gets you into roughly 1,500 lounges worldwide. The catch: in high-traffic hubs like LAX, JFK, and Heathrow, Priority Pass lounges are frequently at capacity by 6pm, and the food quality ranges from "decent charcuterie" to "sad pretzels in a bowl." Don't build your itinerary around Priority Pass. Treat it as a floor, not a plan.
Centurion Lounges, exclusive to Amex Platinum and higher, are a different animal. The Centurion Lounge at DFW alone spans two floors with a full-service restaurant. The one at LAX overlooks the tarmac and pours a genuinely good Argentine Malbec. But Amex has been quietly tightening guest policies since 2023, and as of 2025 Platinum cardholders get complimentary access for themselves plus two guests only if they've spent $75,000 or more on the card in the prior calendar year. Below that threshold, guests cost $50 each. Read the fine print before you assume you're walking in with your whole entourage.
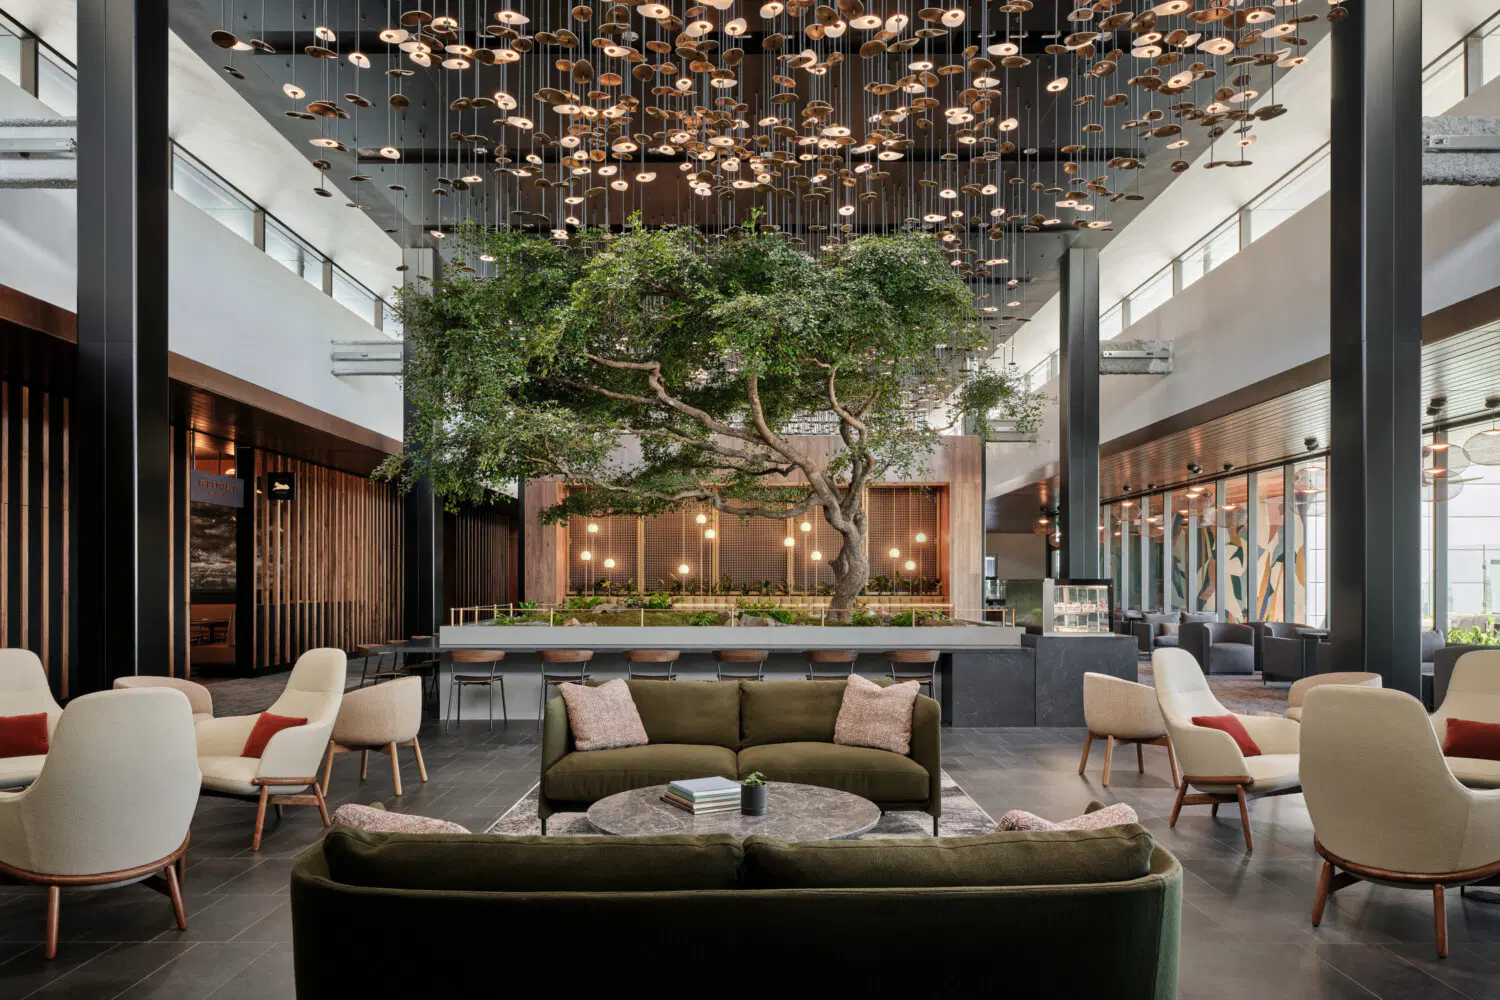
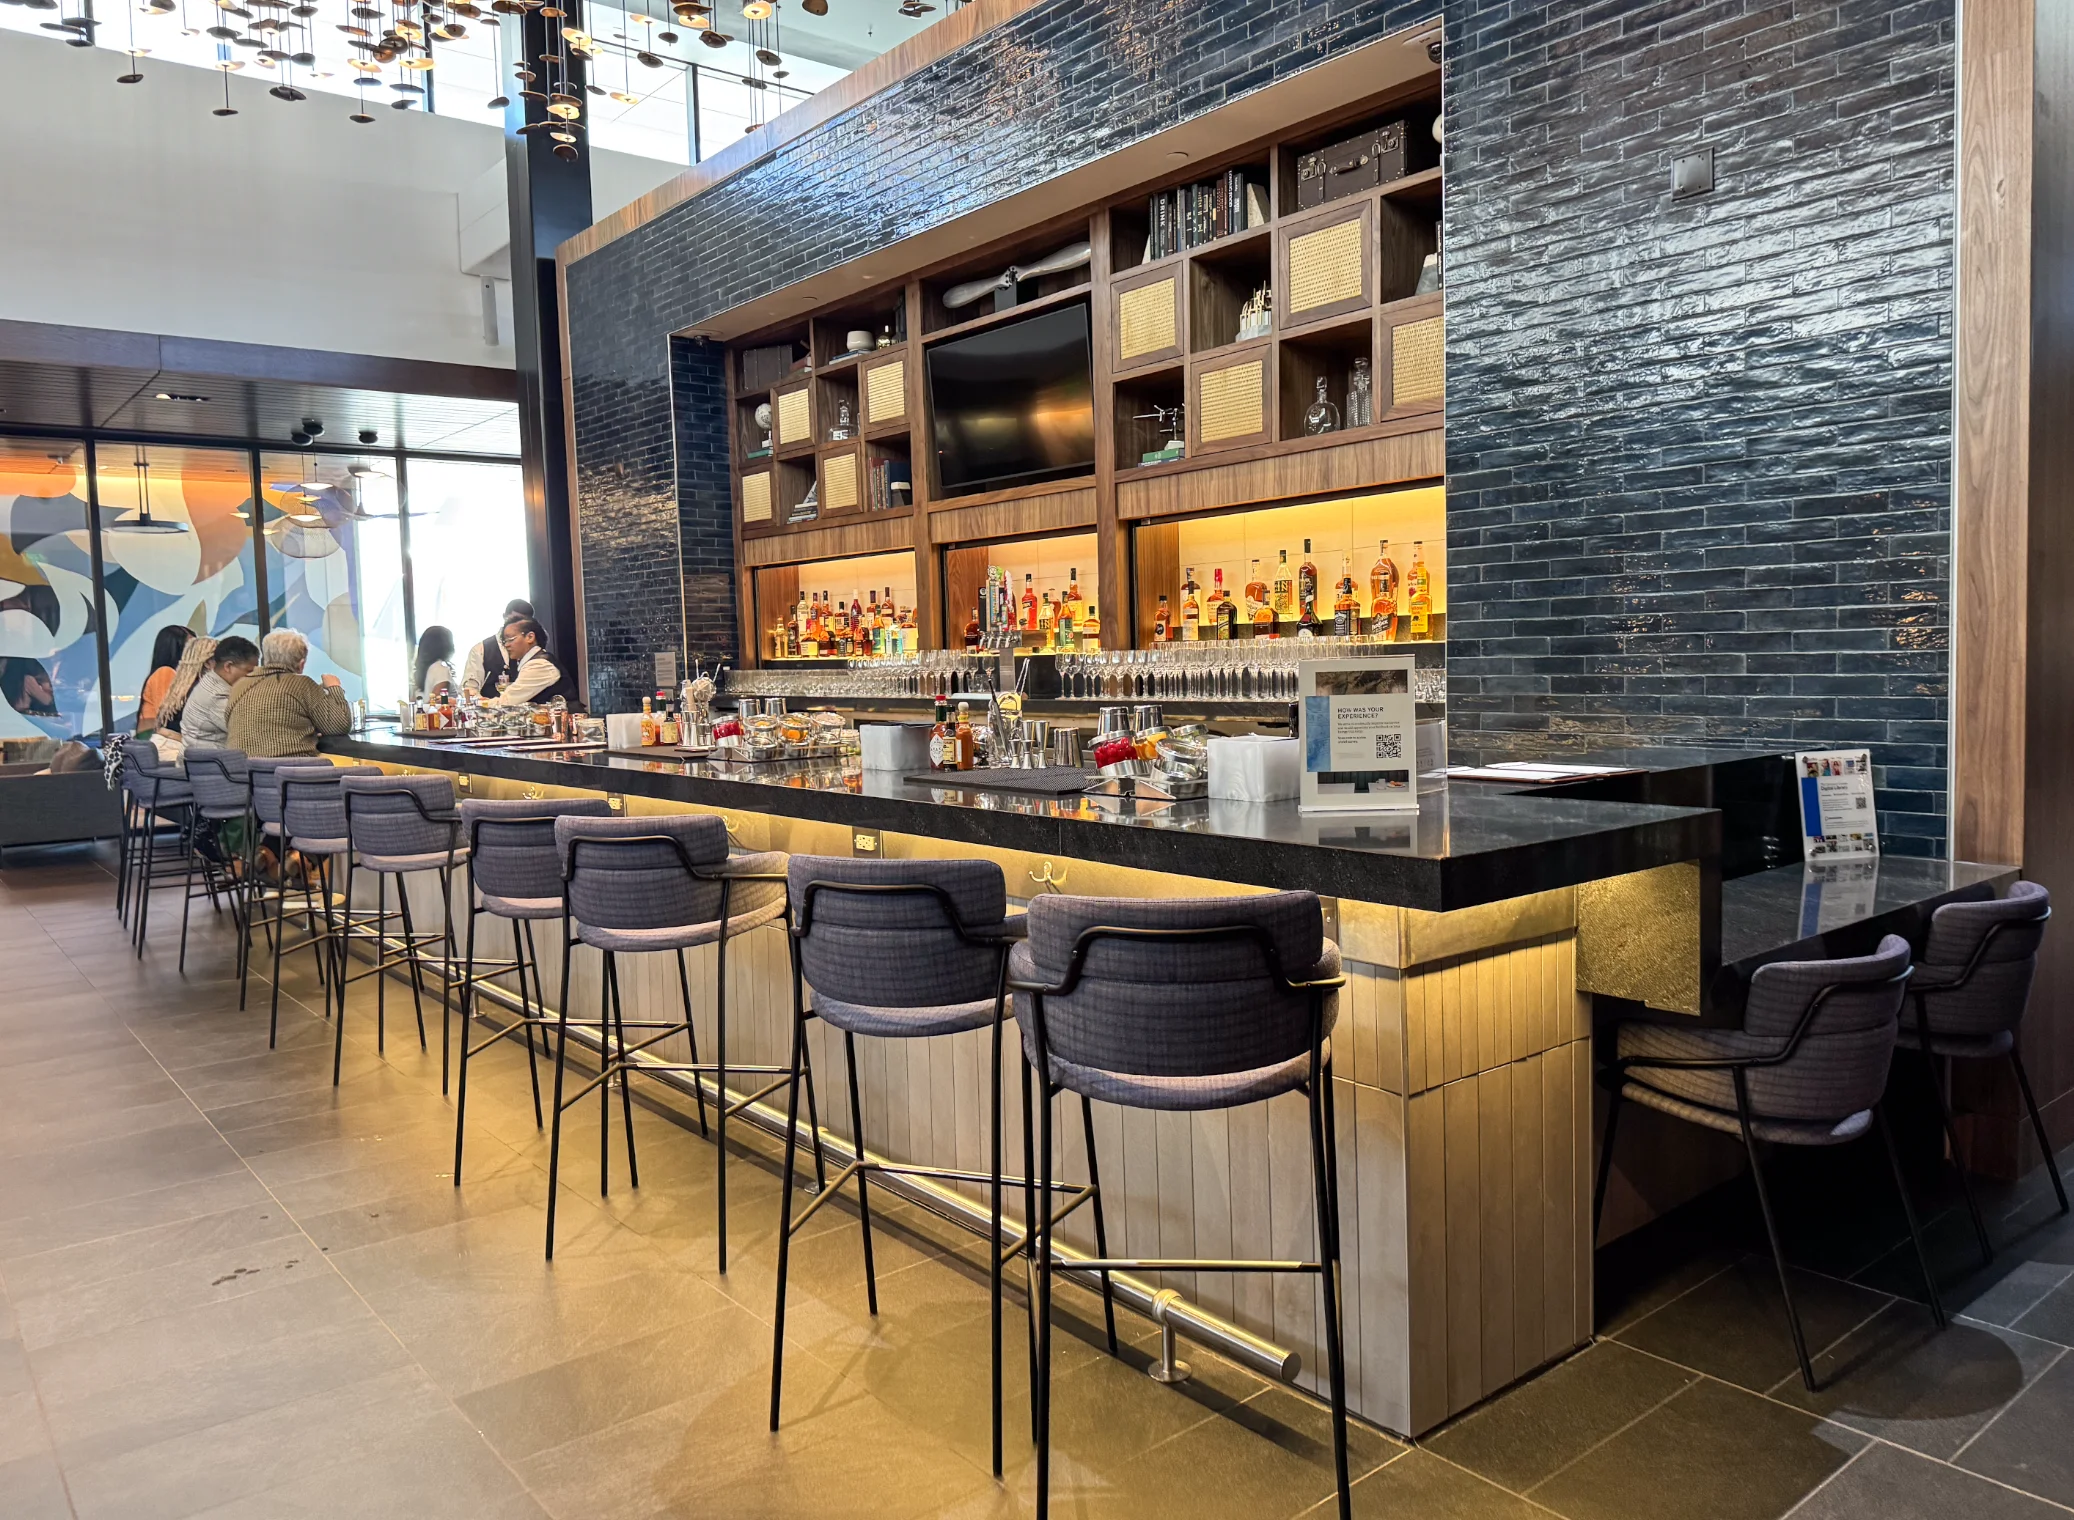
Newer Centurion Lounges are built like boutique hotel lobbies — but since 2025, Platinum guests are free only after $75,000 in annual card spend; below that, each guest costs $50.
Capital One Lounges, a newer network exclusive to Venture X (and the business version), currently operate in Dallas-Fort Worth, Washington Dulles, and Denver, with more announced for 2026 in Charlotte and Las Vegas. They're excellent: cold brew on tap, grab-and-go that doesn't taste like an afterthought, actual daylight. The limitation is obvious. Three cities is not a network yet. If your routing doesn't touch DFW, IAD, or DEN, this perk is theoretical.
Plaza Premium Lounges, included on both cards through separate arrangements, fill in some of the international gaps, particularly in Asia-Pacific hubs where Priority Pass coverage thins out.
Insider Strategy
Before you assume a lounge perk justifies a card's annual fee, map it against your actual routing for the next twelve months. A Centurion Lounge you'll use six times a year at $50 for guests is worth roughly $300 in access value. A Priority Pass you'll use twice because your hub airports don't have decent participating lounges is worth closer to zero.
The Annual Credit Math: Does It Actually Offset the Fee?
Card issuers love to advertise "credits that more than offset the annual fee." Sometimes that's true. Often it's true only if you're disciplined about using every credit, which most cardholders aren't.
The Venture X offers a $300 annual travel credit redeemable through Capital One's own portal, plus 10,000 anniversary miles worth roughly $100 at minimum redemption value. That's $400 in value against a $395 fee, before you've spent a dollar on the card. The catch: the $300 credit only works through Capital One Travel, which prices flights competitively but not always at the lowest available fare. You're trading some booking flexibility for the credit.
The Amex Platinum's credit stack is more elaborate and, frankly, more annoying to actually use. There's a $200 airline incidental credit tied to one specific airline you designate annually. There's a $200 hotel credit usable only at Fine Hotels & Resorts or The Hotel Collection properties. There's a $240 digital entertainment credit split across specific streaming services. There's a $155 Walmart+ credit nobody asked for. Add it up and Amex claims over $1,500 in annual value. In practice, most cardholders capture $600 to $900 of it, because the credits are fragmented across categories that don't map cleanly onto how anyone actually spends money.
The lesson: a credit you have to remember to use in six different micro-transactions across the year is worth less than its face value. Discount accordingly. If you're not going to manually track a $200 hotel credit that only applies to a specific booking portal, don't count it in your math.
Insurance and Protections That Actually Matter at This Price Point
This is the category nobody talks about enough, and it's the one that matters most once your average ticket price crosses four figures.
Both the Venture X (Visa Infinite) and the Platinum (backed by its own set of underwriters) offer primary rental car collision coverage, meaning you can decline the rental company's collision damage waiver entirely and rely on the card. On a weeklong rental of a full-size SUV, that waiver typically runs $35 to $55 a day. Skip it, pay with the right card, and you've just saved $250 to $400 per trip without giving up coverage.
Both flagship cards reimburse up to $500 in meals and hotel once a delay passes six hours — coverage that pays for itself the first time a mechanical strands you overnight.
Trip delay reimbursement is the other underrated one. Both cards trigger at six-plus hours of delay or an overnight disruption, and both will reimburse reasonable expenses, meals, hotel, incidentals, up to $500. If you fly premium cabins with any frequency, you will eventually sit at a gate for six hours because of a mechanical issue or a crew timeout. Having $500 of coverage baked into how you paid for the ticket is not a nice-to-have. It's the difference between an annoying afternoon and an annoying afternoon that also costs you $400 out of pocket.
Lost luggage reimbursement matters less if you're the type who never checks a bag, which, if you're flying lie-flat with a generous checked allowance, you should reconsider. Business class tickets on most carriers include two checked bags at 70 pounds each. Use the allowance. Just make sure your card covers you if the bag doesn't show up in Milan.
Read the underwriting, not the marketing copy
Card issuers change insurance terms more often than they announce it. Capital One tightened certain benefit terms on Visa Infinite products in 2024, and Amex has done the same with its Platinum protections more than once. Pull the actual guide to benefits (a PDF, usually buried in your online account) once a year. Don't rely on a blog post, including this one, for the current fine print.
Elite Status Perks: The Multiplier Effect
Hertz President's Circle status, included with the Venture X, is a legitimately useful perk if you rent cars with any regularity. Skip-the-counter service and guaranteed upgrades sound like small things until you're the person standing in the Hertz line at 11pm at LAX while everyone with status walks straight to their car. On a dozen rentals a year, that's easily two or three hours of your life back, and time is the one thing none of these perks can actually manufacture more of.
The Amex Platinum's hotel status game is arguably stronger on paper: complimentary Gold status with Marriott Bonvoy and Hilton Honors. In practice, Gold status at either chain gets you a modest breakfast credit and maybe a room upgrade if the property isn't full, which, at the properties premium travelers actually stay at, it usually is. Don't overweight this perk. It's real, it's just smaller than the marketing suggests.
How Credit Cards Actually Fit Around Consolidator Bookings
Here's where we diverge hardest from the standard credit card review, because this is the part that actually matters for how CEOFLIGHTS clients operate.
A credit card is a tool for earning, insurance, and lounge access. It is not, and should not be, your primary tool for pricing the seat itself. Portal bookings through Capital One Travel or Amex Travel are convenient, and the built-in credits make them feel efficient, but they are rarely the cheapest way to buy a J-class ticket on a long-haul route. Portals mark up fares to fund the loyalty economics; that's not a conspiracy, it's just how the math works.
Consider a New York to London round trip in business class. Booked directly or through a major portal in shoulder season 2026, list fares on carriers like British Airways or Virgin Atlantic commonly run $5,200 to $6,800 round trip in J. Through a consolidator relationship, the same cabin, same dates, same fare rules in most cases, prices out $1,800 to $2,600 lower, because consolidators buy inventory in bulk from the airlines at negotiated net rates and pass a meaningful chunk of that discount through.
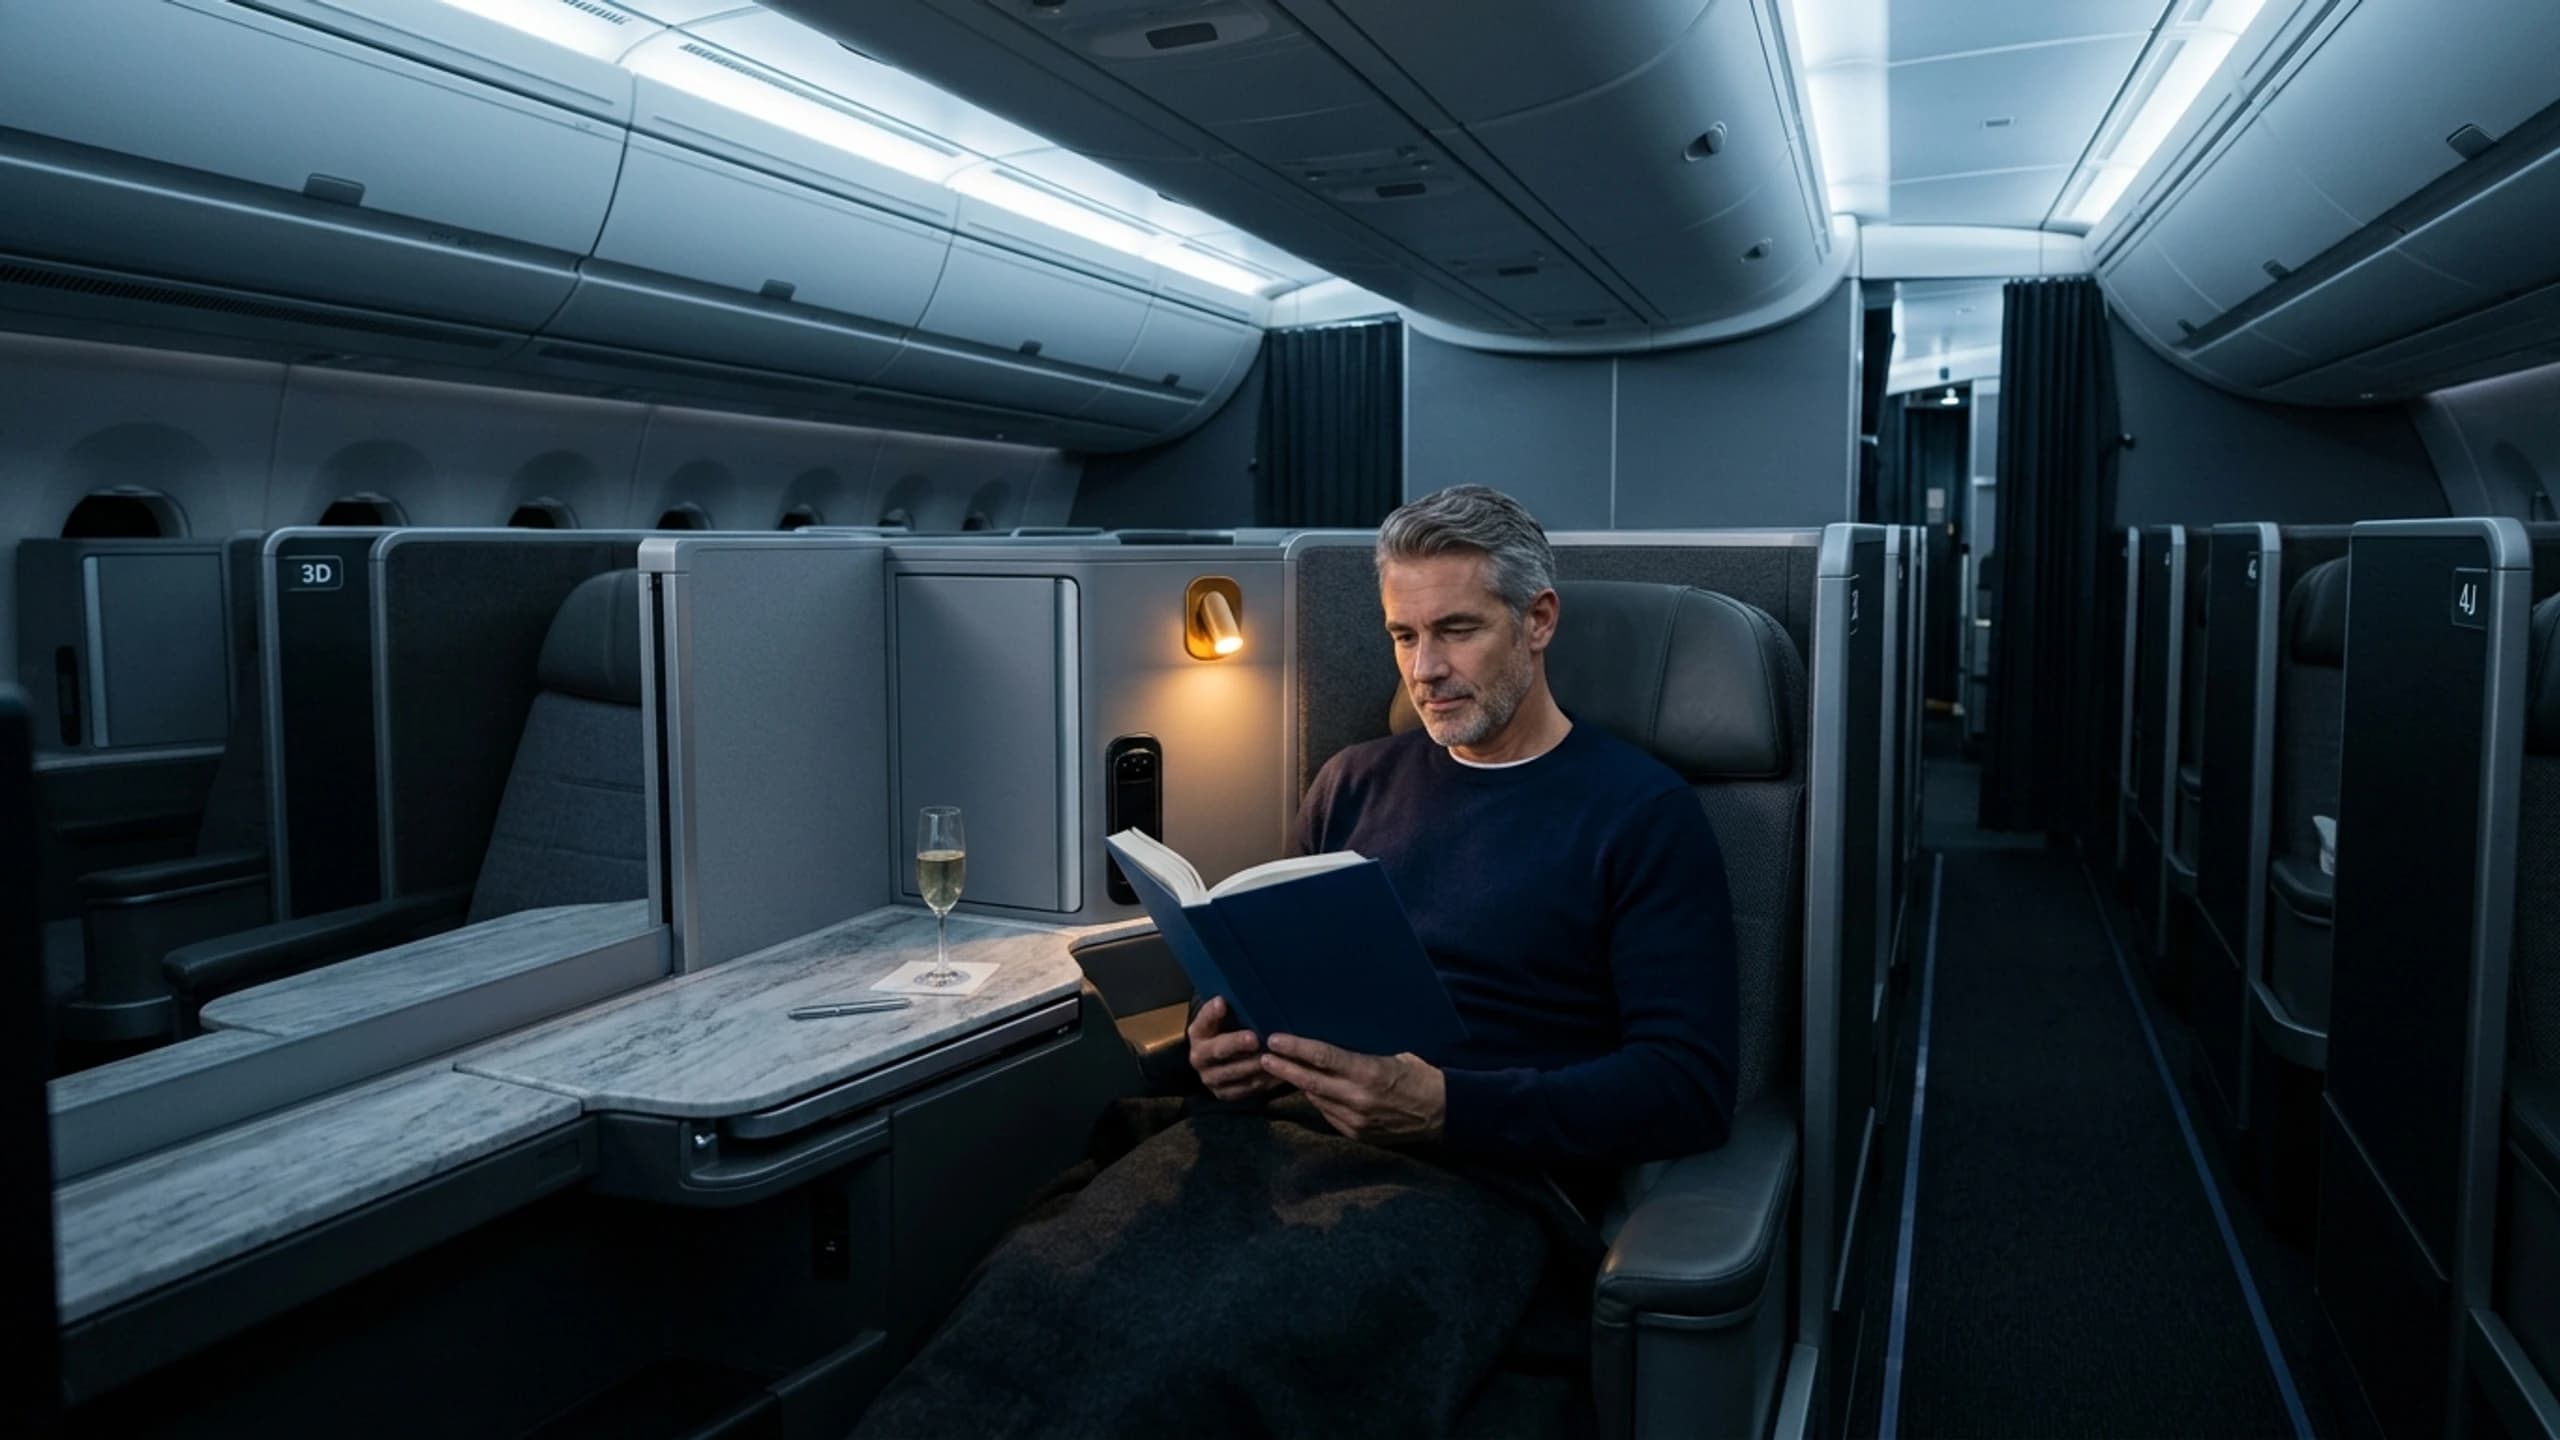
That's the seat in question: British Airways' Club Suite, with a door and direct aisle access, on one of the busiest premium routes in the world. Whether you sit in it at list price or at a negotiated rate has nothing to do with which card is in your wallet. It comes down to which channel the ticket came through, and for a solo executive or a couple, a well-sourced consolidator business class fare remains the more rational buy nine times out of ten.
The strategic move, then, is to use the card for what it's good at (points accrual, insurance, lounge access on the day of travel) and use a consolidator relationship like CEOFLIGHTS for what it's good at (actually pricing the seat correctly). Book the fare through the consolidator, pay with the card that gives you the best per-dollar return and the strongest purchase protection, and you've captured value on both ends of the transaction. If you want to see what that looks like on your own routes, talk to a CEOFLIGHTS travel manager before you commit to six business class seats on a Tuesday morning departure at whatever the portal happens to show.
Insider Strategy
Never book a consolidator fare directly through a card's travel portal integration. Call or book direct with the consolidator, then pay with your preferred card as a straight purchase. You keep the insurance and earning rate; you lose nothing.
The Redemption Trap: Points Are Not Cash, Stop Treating Them Like It
Both flagship cards let you redeem miles or points at a flat rate toward travel purchases: one cent per Capital One mile, roughly similar for Amex Membership Rewards depending on the redemption method. That's a fine floor. It is not where the real value lives.
The real value lives in transferring points to airline and hotel partners and booking premium award space directly. A one-way business class award on Air France's A350 between New York and Paris can price at 50,000 to 60,000 Capital One miles transferred to Flying Blue, depending on availability tier. At the flat one-cent redemption rate, that same 55,000 miles buys you a $550 travel credit. Transferred and booked as an award seat on a route where cash fares run $3,000 to $4,000 one-way, you've captured six to seven times the flat-rate value.
The problem: award availability for premium cabins has gotten tighter, not looser, over the past three years, as airlines lean harder into dynamic pricing and shrink the number of seats released to partner programs. Chasing a 50,000-mile Flying Blue award to Paris in July is a fine hobby if you have flexible dates and patience. It is not a reliable travel strategy if you need to be in Paris on a specific Tuesday for a board meeting. For fixed-date, must-fly travel, a consolidator fare bought with cash and points earned in parallel beats hunting for saver-level award space almost every time.
Don't build your entire travel budget around the assumption you'll find that unicorn redemption. Build it around reliable cash pricing, and treat great redemptions as upside when they show up.
Building the Right Two-Card Stack for 2026
If you're starting from scratch, here's the honest recommendation, no affiliate incentive attached: carry both flagship cards if the spend supports it, and lean on each for what it does best.
Put everyday and business spend on the Venture X. Its flat 2x return on every purchase with no bonus category gymnastics is simply the best baseline rate available on a personal card right now, and the $300 travel credit plus 10,000 anniversary miles genuinely does offset most or all of the $395 fee for anyone who uses even one of those credits deliberately.
Carry the Amex Platinum specifically for the Centurion Lounge network and for airline-specific incidental credits if you fly one carrier heavily enough to make that $200 credit trivially easy to burn on seat upgrades or bag fees. At $895 a year, the Platinum only earns its keep if you're actually walking into Centurion Lounges four or more times a year, or if the hotel and airline credits map cleanly onto spend you were making anyway.
Four or more Centurion visits a year is roughly the break-even point for the Platinum's $895 fee — the full-service bar is a large part of why frequent DFW, LAX, and SEA flyers keep the card.
If you can only justify one card, the math favors the Venture X for most people. Lower fee, simpler credit structure, and a lounge network that, while smaller, is genuinely excellent where it exists. The Platinum is the better card if your routing runs heavily through Centurion cities (DFW, LAX, SEA, LGA, and a growing international list) and you're disciplined enough to actually use the fragmented credits.
Authorized users change the math
Both cards allow multiple authorized users at no extra cost on the Venture X, and at additional cost on the Platinum. If you're outfitting a spouse or a business partner with the same lounge access and insurance, the per-person cost of the Venture X drops meaningfully. Run that math before assuming the Platinum's richer perks justify its higher fee for a two-person household.
What We'd Actually Carry Into 2026
Strip away the marketing copy and here's the shortlist that matters: a card with a lounge network you'll genuinely use based on your real routing, primary rental car insurance so you stop paying collision waivers, trip delay coverage that pays out at six hours rather than twelve, and a flat everyday earning rate north of 2x so you're not doing mental math on bonus categories at checkout.
Everything past that is marginal. The $155 credit for a retailer you don't shop at, the airline incidental credit tied to a carrier you fly twice a year, the metal card weight, the anniversary miles you forget you have, these are rounding errors compared to getting the actual seat priced correctly in the first place.
That's the piece we'd leave you with. A card is infrastructure. It earns you a rate, protects you when things go wrong, and gets you somewhere comfortable to sit before a flight. It has never once, in the history of these programs, been the reason someone paid the right price for a business class ticket to Tokyo. That still comes down to knowing where to source the fare, which is a different skill entirely, and one worth outsourcing to people who do it for a living. If you're booking for a group, or for a route you fly every month, a personal travel manager can source unpublished business class fares and handle seat selection and changes, which leaves the card to do the job it's actually good at.
Content creator and business travel specialist at CEOFLIGHTS, bringing you the latest insights, tips, and trends in premium business and first-class travel.
Become the CEO of Your Journey
You take the lead. Your dedicated Personal Travel Manager handles every detail.